
 HOME
 WAEC
 NECO
 07048281409

BEST EXPO RUNZ ASSISTANCE WEBSITE. NO.1 BEST DELIVERY OF EXAM RUNZ
100% GUARANTEE OF GETTING ANSWERS MIDNIGHT..IT’S OUR CULTURE, NO DOUBT
===================================
F/ACCOUNT
01-10: DADBDDCBBA
11-20: CACAECACED
21-30: ABADEDDECA
31-40: BAACCCDEAC
41-50: AAAEDBDDBE
51-60: EBDDCBBCCB
COMPLETED
═══════════════════════════
SECTION A: ANSWER TWO(2) QUESTIONS ONLY
(1a)
(i) Three Column Cash Book: A three-column cash book is a special book of original entry and a ledger account used to record all cash transactions, bank transactions, and cash discounts in a business. It contains three money columns on both the debit and credit sides for cash, bank, and discount, thereby eliminating the need to maintain separate cash and bank accounts in the ledger.
(ii) Cash Discount: Cash discount is a reduction in the amount payable granted by a seller to a buyer as an incentive for making prompt or immediate payment within a specified period. It encourages early settlement of debts, improves the seller’s cash flow, and reduces the possibility of bad debts.
(iii) Working Capital: Working capital is the excess of current assets over current liabilities. It represents the amount of funds available for financing the day-to-day operations of a business and enables the business to meet its short-term financial obligations as they fall due.
(iv) Gross Profit: Gross profit is the excess of net sales over the cost of goods sold during an accounting period. It is the first profit earned by a business before deducting operating expenses such as salaries, rent, and other administrative expenses. Gross Profit = Net Sales − Cost of Goods Sold.
(v) Net Profit: Net profit is the final profit earned after deducting all operating, administrative, selling, and other business expenses from the gross profit. It represents the actual earnings of the business available for distribution or reinvestment. Net Profit = Gross Profit − Operating Expenses.
(1b)
(i) Business owners (Proprietors)
(ii) Management
(iii) Shareholders
(iv) Creditors
(v) Debtors
(vi) Investors
(vii) Banks and other financial institutions
(viii) Government and tax authorities
(ix) Employees and trade unions
(x) Potential investors
═══════════════════════════
(2a)
A partnership is a form of business organisation in which two or more persons (not exceeding 20 in ordinary business and 10 in banking business) agree to contribute capital, share profits and losses, and jointly own and manage a business according to the terms contained in a partnership agreement or partnership deed.
(2b)
(i) Name and address of the partnership.
(ii) Names and addresses of the partners.
(iii) Capital contribution of each partner.
(iv) Profit and loss sharing ratio.
(v) Interest on capital and drawings.
(vi) Salaries, commissions, or allowances payable to partners.
(2c)
=DIFFERENCES=
(i) A Receipts and Payments Account records all cash receipts and payments whether capital or revenue and whether relating to the current, past, or future period, while an Income and Expenditure Account records only revenue incomes and expenses relating to the current accounting period.
(ii) A Receipts and Payments Account is prepared on a cash basis, while an Income and Expenditure Account is prepared on the accrual basis.
(iii) A Receipts and Payments Account begins with the opening cash and bank balances and ends with closing balances, while an Income and Expenditure Account begins with income and expenditure items and ends with either surplus or deficit.
=SIMILARITIES=
(i) Both are prepared mainly by non-profit-making organisations and are used in preparing their final accounts.
═══════════════════════════
(3a)
A capital market is a financial market where medium-term and long-term funds are raised and traded through financial instruments such as shares, debentures, government bonds, and other securities. It provides businesses and governments with long-term capital for investment and expansion.
(3b)
(i) Unpresented Cheques: Cheques issued by the business may have been recorded in the cash book but have not yet been presented to the bank for payment. Therefore, they reduce the cash book balance but do not immediately affect the bank statement.
(ii) Uncredited Lodgements (Outstanding Deposits): Cash or cheques paid into the bank may have been recorded in the cash book but may not yet have been credited by the bank. This causes the cash book balance to be higher than the bank statement balance.
(iii) Bank Charges and Commission: The bank may deduct charges, commission, or service fees directly from the customer’s account before the business becomes aware of them. These deductions appear in the bank statement before they are entered in the cash book.
(iv) Direct Credits and Standing Orders: Customers may pay money directly into the business account, or the bank may make payments through standing orders or direct debits. These transactions appear first in the bank statement and may not yet be recorded in the cash book.
(v) Errors: Mistakes made either by the business when recording transactions in the cash book or by the bank when preparing the bank statement can also cause differences between the two balances.
═══════════════════════════
(4a)
(i) Both involve two or more persons carrying on a business together.
(ii) Both are established with the aim of making profit.
(iii) In both, the parties contribute capital or resources toward the business.
(iv) Profits and losses are shared according to an agreed ratio.
(4b)
A trade discount is a reduction in the listed or catalogue price of goods granted by a seller to a buyer, usually because of bulk purchases or trade relationships. It is deducted before payment is made and is not recorded in the accounting books.
(4c)
Under Assets
(i) Land
(ii) Premises
(iii) Debtors
(iv) Cash in hand
(v) Subscription in arrears
(vi) Stock
(vii) Motor van
Under Liabilities
(i) Creditors
(ii) Bank overdraft
(iii) Subscription in advance
(iv) Debenture
(v) Loan
═══════════════════════════
SECTION B: ANSWER THREE(3) QUESTIONS ONLY
(6)
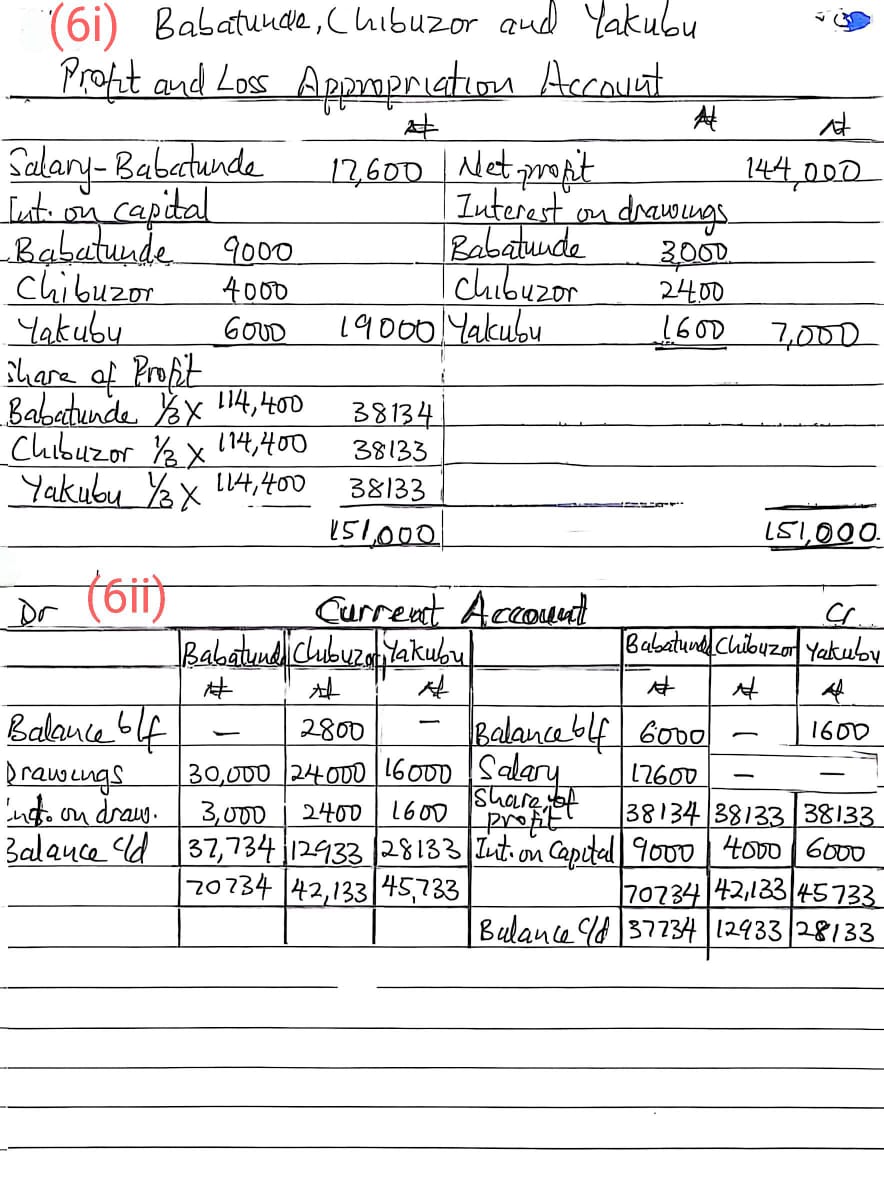
═══════════════════════════
(7)
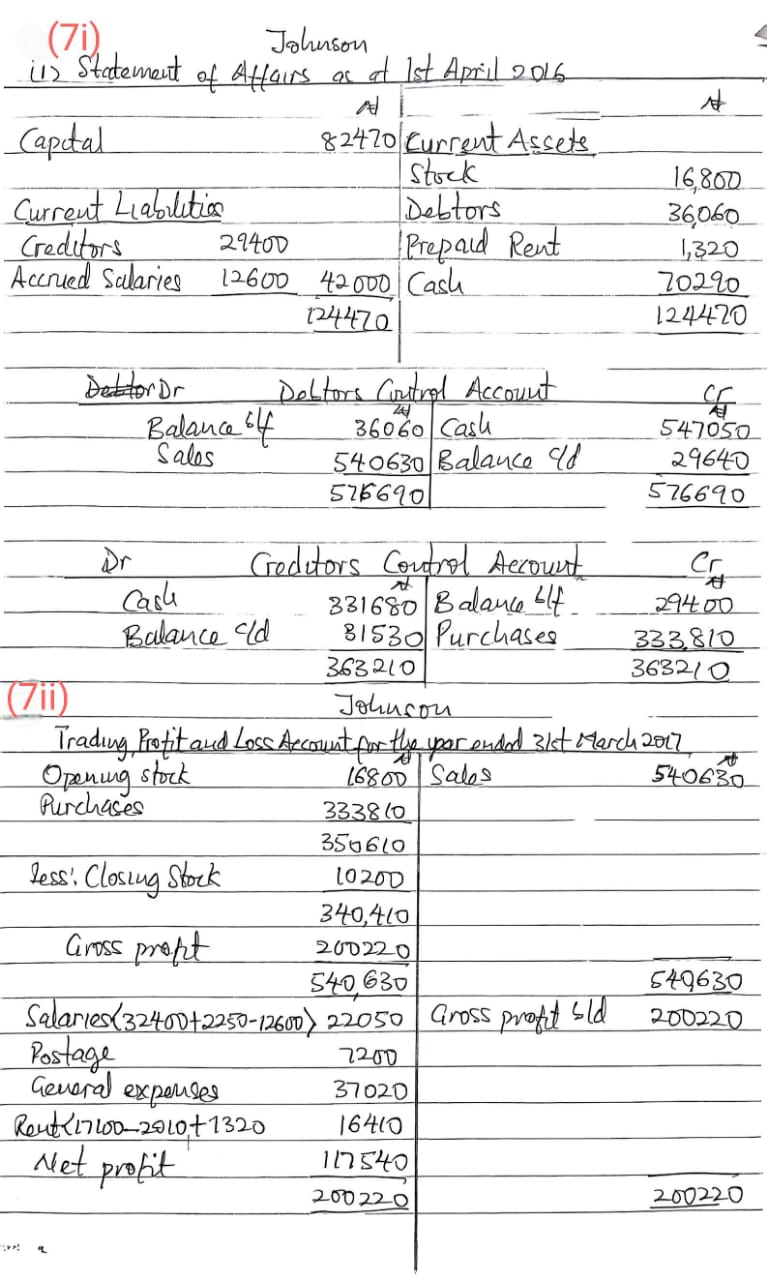
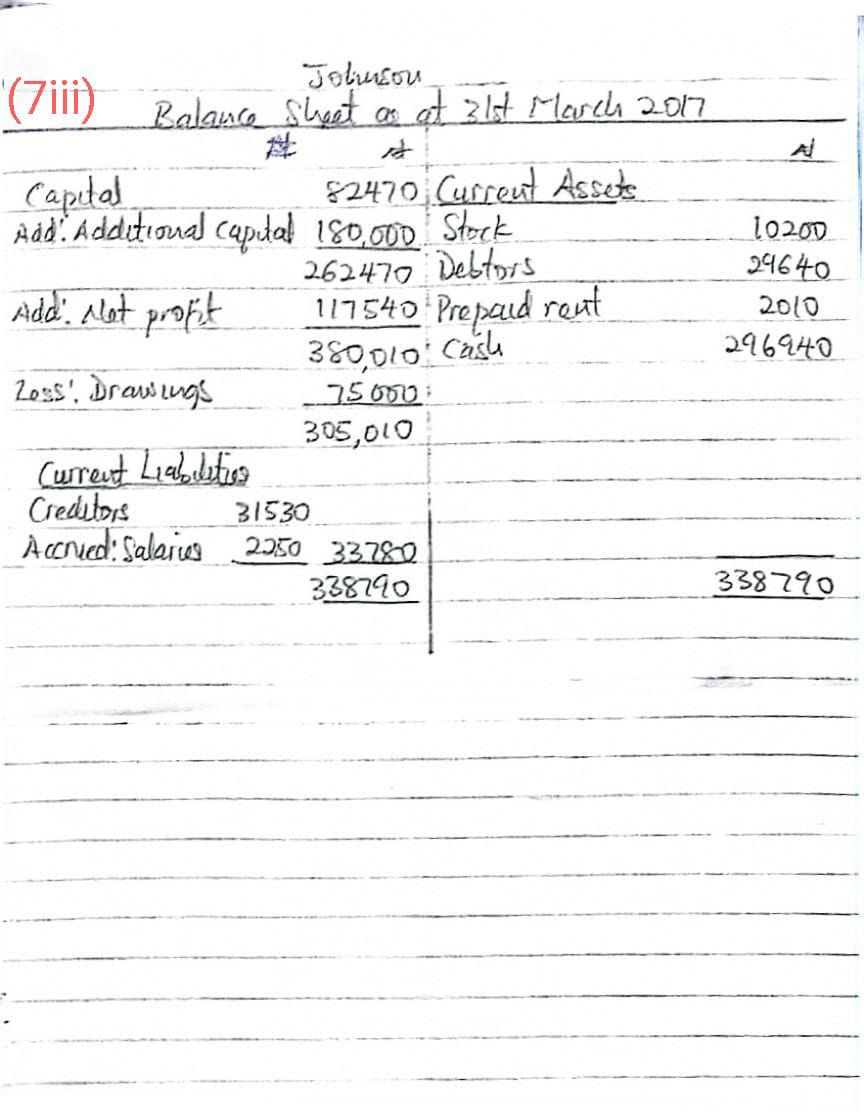
═══════════════════════════
(8)
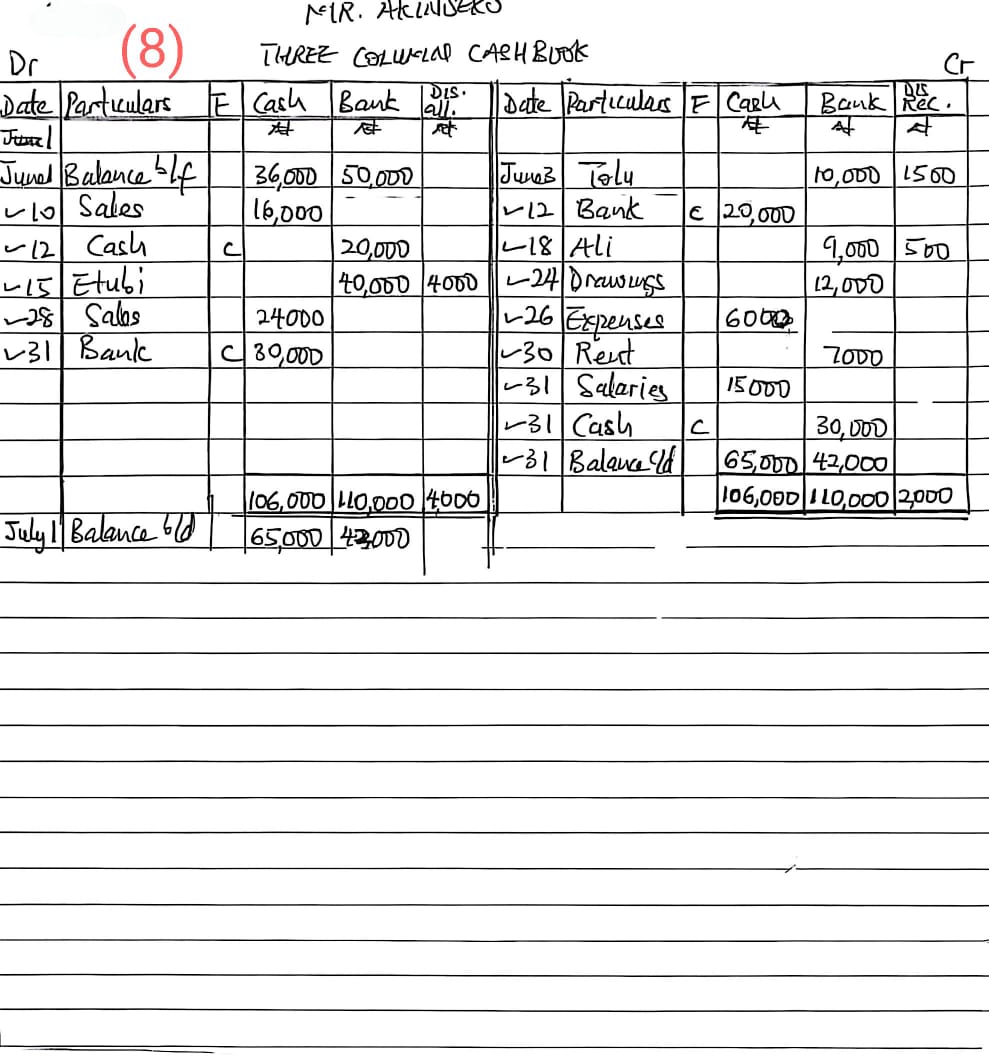
═══════════════════════════
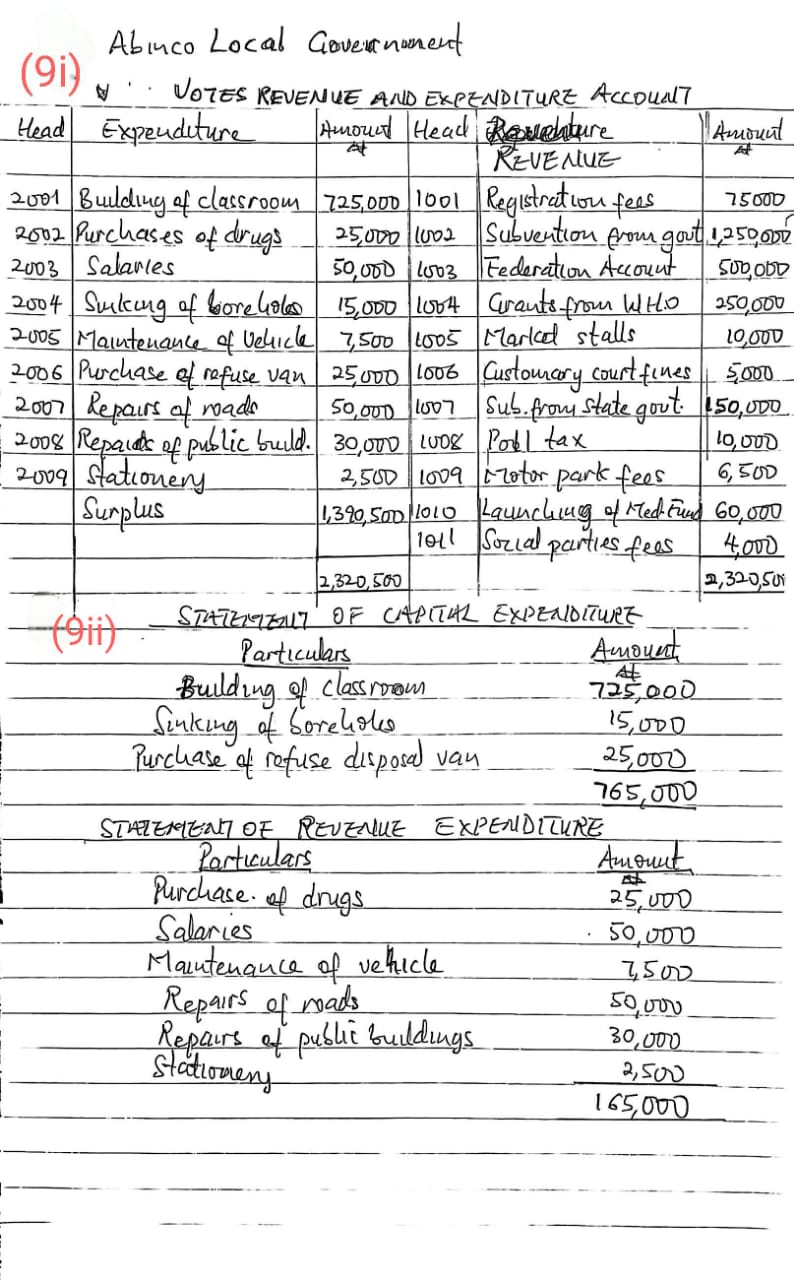
(9)
═══════════════════════════
COMPLETED….We Remain Your Favourite Site.
Ensure You Subscribe For Your Next Paper
===================================
Leave a Reply